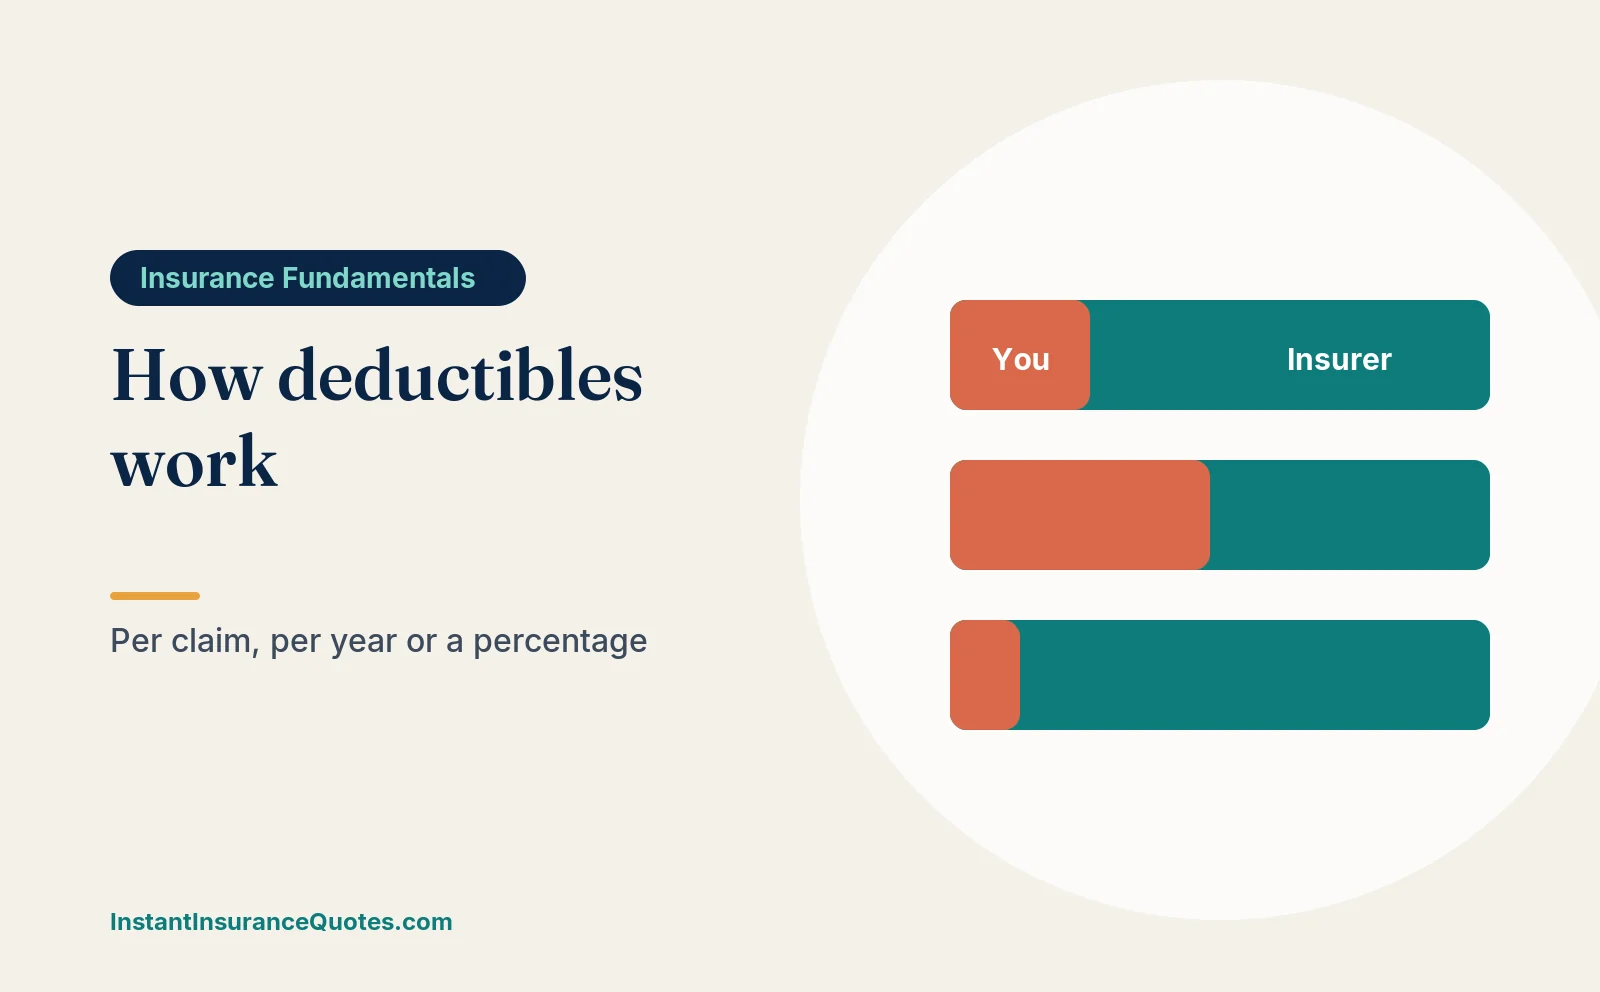
A deductible is the part of a covered loss you pay before insurance pays. That sounds simple, but deductibles work differently across policies. Car and renters deductibles usually apply to each claim. Pet and health deductibles usually apply once per year. Some home deductibles are a percentage of the house's insured value rather than a dollar amount, and some coverages have no deductible at all.
This guide explains each type with examples, shows how to decide how high your deductibles should be, and highlights the coverages within common policies where no deductible applies.
The main kinds of deductibles
| Type | How it works | Where you see it |
|---|---|---|
| Per-claim (per-occurrence) dollar deductible | A fixed amount, such as $500, subtracted from each covered claim | Auto collision and comprehensive; renters; homeowners all-other-perils |
| Percentage deductible | A percentage of the dwelling coverage limit, not of the damage | Home wind/hail, named storm or hurricane, earthquake policies |
| Annual deductible | Met once per policy year, then reimbursement applies to later covered bills | Most pet insurance; health insurance |
| Per-condition deductible | Applies once to each separate condition, sometimes for life | Some pet insurance plans |
| Disappearing or vanishing deductible | Shrinks for each claim-free year, as a paid feature or reward | Some auto and home programs |
| No deductible | Coverage pays from the first dollar up to its limit | Liability coverages; renters loss of use in many forms; auto glass in some states or policies |
Car insurance deductibles
On a car policy, collision and comprehensive each carry their own deductible, commonly $250 to $1,000 or more, applied each time you file. Liability coverage, which pays others when you cause a crash, has no deductible. If another driver hits you and their insurer pays, you owe no deductible; if you use your own collision coverage, you pay it and your insurer may try to recover it from the at-fault driver. Our car deductible guide covers collision vs. comprehensive choices in detail.
Home and renters deductibles
Renters and homeowners policies usually have an all-other-perils dollar deductible for property claims. In the Nevada-filed renters form we reviewed, the deductible applies to property coverages but explicitly not to loss of use (extra living expenses), and liability and medical payments coverages carry no deductible at all.
Homes in wind, hail or hurricane-exposed areas may also carry a separate percentage deductible. It is calculated on the dwelling limit, not the damage. On a $350,000 dwelling limit:
| Wind/hail deductible | Dollar amount you pay first |
|---|---|
| 1% | $3,500 |
| 2% | $7,000 |
| 5% | $17,500 |
Fannie Mae caps acceptable deductibles on the one- to four-unit homes it finances at 5 percent of the property insurance coverage amount, applied to each separate deductible. Your lender may set a lower limit. See our home deductible guide for how these play out in storm claims.
Pet insurance deductibles
Pet plans usually use an annual deductible paired with a reimbursement percentage. You pay covered bills up to the deductible, then the plan reimburses a share, such as 80 percent, of the rest. A few use per-condition deductibles, which can be better for one big problem and worse for several small ones.
| Covered vet bills in one year | Annual $250 deductible, 80% reimbursement | Per-condition $250 deductible, 80% |
|---|---|---|
| One $3,000 surgery | Plan pays $2,200 | Plan pays $2,200 |
| Three unrelated $600 illnesses | ($1,800 − $250) × 80% = $1,240 | 3 × ($600 − $250) × 80% = $840 |
| Same chronic condition, second year, $1,500 | Deductible resets: $1,000 | If per-condition for life: $1,200 |
The NAIC Pet Insurance Model Act requires insurers in adopting states to disclose deductibles, coinsurance and limits before purchase. Our pet reimbursement guide has a full calculator walkthrough.
A note on health insurance
Health insurance uses an annual deductible with copays, coinsurance and an out-of-pocket maximum. HealthCare.gov defines the deductible as the amount you pay for covered services before your plan starts to pay, noting that some services, such as certain preventive care, may be covered before you meet it. Health plans are a separate topic; see our guide to deductibles, copays and coinsurance.
Choosing your deductible: a break-even test
A higher deductible lowers your premium because you keep more of the small losses. The question is whether the savings are worth the extra risk. A simple test:
- Get two quotes that differ only by deductible.
- Divide the extra deductible by the yearly savings. That is the number of claim-free years it takes to break even.
- Compare that with how often you have actually filed claims.
- Check that you could pay the higher deductible tomorrow from savings.
| Lower deductible | Higher deductible | |
|---|---|---|
| Deductible | $500 | $1,000 |
| Yearly premium (hypothetical) | $1,180 | $1,060 |
| Extra out-of-pocket per claim | $500 | |
| Yearly savings | $120 | |
| Years to break even | 4.2 years per claim |
If you file a claim less than once every four years, the higher deductible likely comes out ahead. Our free deductible savings calculator does this math in your browser.
Rules of thumb that trip people up
- One event, several policies. A storm that damages your home and your car may trigger a home deductible and an auto comprehensive deductible.
- One event, one deductible. Most property policies apply one deductible per occurrence, even if several rooms or items are damaged.
- Deductibles do not count toward limits. Your coverage limit is the most the insurer pays; the deductible comes off the loss, not off the limit, in most property policies. Read the loss payment section to confirm.
- Small claims and premiums. Filing a claim barely above the deductible can raise future premiums by more than the payout.
When to revisit your deductibles
Deductible amounts are often set at purchase and forgotten. Revisit them when:
- Your savings change. A bigger emergency fund can justify a higher deductible and lower premium; a drained fund after a home purchase may call for a lower one.
- You buy a home in a new region. Percentage wind, hail or hurricane deductibles may appear for the first time. Convert them to dollars.
- Your car ages. On an older car worth a few thousand dollars, a $1,000 collision deductible can consume much of any payout. At some point dropping collision may make sense; see what full coverage means.
- Your pet is diagnosed with a chronic condition. An annual deductible resets every year; a per-condition deductible may not. Understand which you have before renewal.
- Premiums rise at renewal. Pricing a higher deductible is one of the quickest ways to offset an increase, if you can afford the risk.
Write each policy's deductibles in dollars on one page, next to your emergency fund balance. If the total of the deductibles you could realistically face in one bad month is larger than the fund, lower a deductible or grow the fund.
Questions readers ask
What is a deductible in insurance?
The amount of a covered loss you pay before the insurer pays. It can be a dollar amount per claim, an annual amount, or a percentage of the insured value.
Is a higher or lower deductible better?
A higher deductible lowers your premium but raises your cost when you claim. It is usually worth it if you could pay it comfortably and rarely file claims.
Do I pay a deductible if I am not at fault in a car accident?
Not if the at-fault driver's insurer pays. If you use your own collision coverage, you pay it, and your insurer may recover it from the at-fault party.
What is a percentage deductible?
A deductible calculated as a percentage of your home's dwelling coverage limit, often used for wind, hail, hurricane or earthquake. A 2% deductible on a $300,000 limit is $6,000.
Does renters insurance have a deductible for liability?
Generally no. Liability and medical payments coverages usually pay without a deductible; the deductible applies to your own property claims.
Sources and further reading
Sources checked October 25, 2026. Figures are the latest published by each source at that date.
- Sample renters policy form CHO-6004 (deductible provisions), filed with the Nevada Division of Insurance
- Fannie Mae Selling Guide B7-3-02: Maximum deductible for one- to four-unit properties
- NAIC Pet Insurance Model Act: required disclosures of deductibles and limits
- HealthCare.gov Glossary: Deductible
- NAIC: Homeowners insurance consumer resources
General educational information, not advice for your situation. Policy wording, state law and the insurer's decision control actual coverage. Written and edited by K.R. Not reviewed by a licensed insurance agent; confirm details with a licensed professional or your insurer. Examples use hypothetical figures unless a source is named. Report a correction.
Use our worksheet to compare premiums, deductibles, and coverage differences. Your entries stay in this browser tab.
Open the quote comparison worksheet