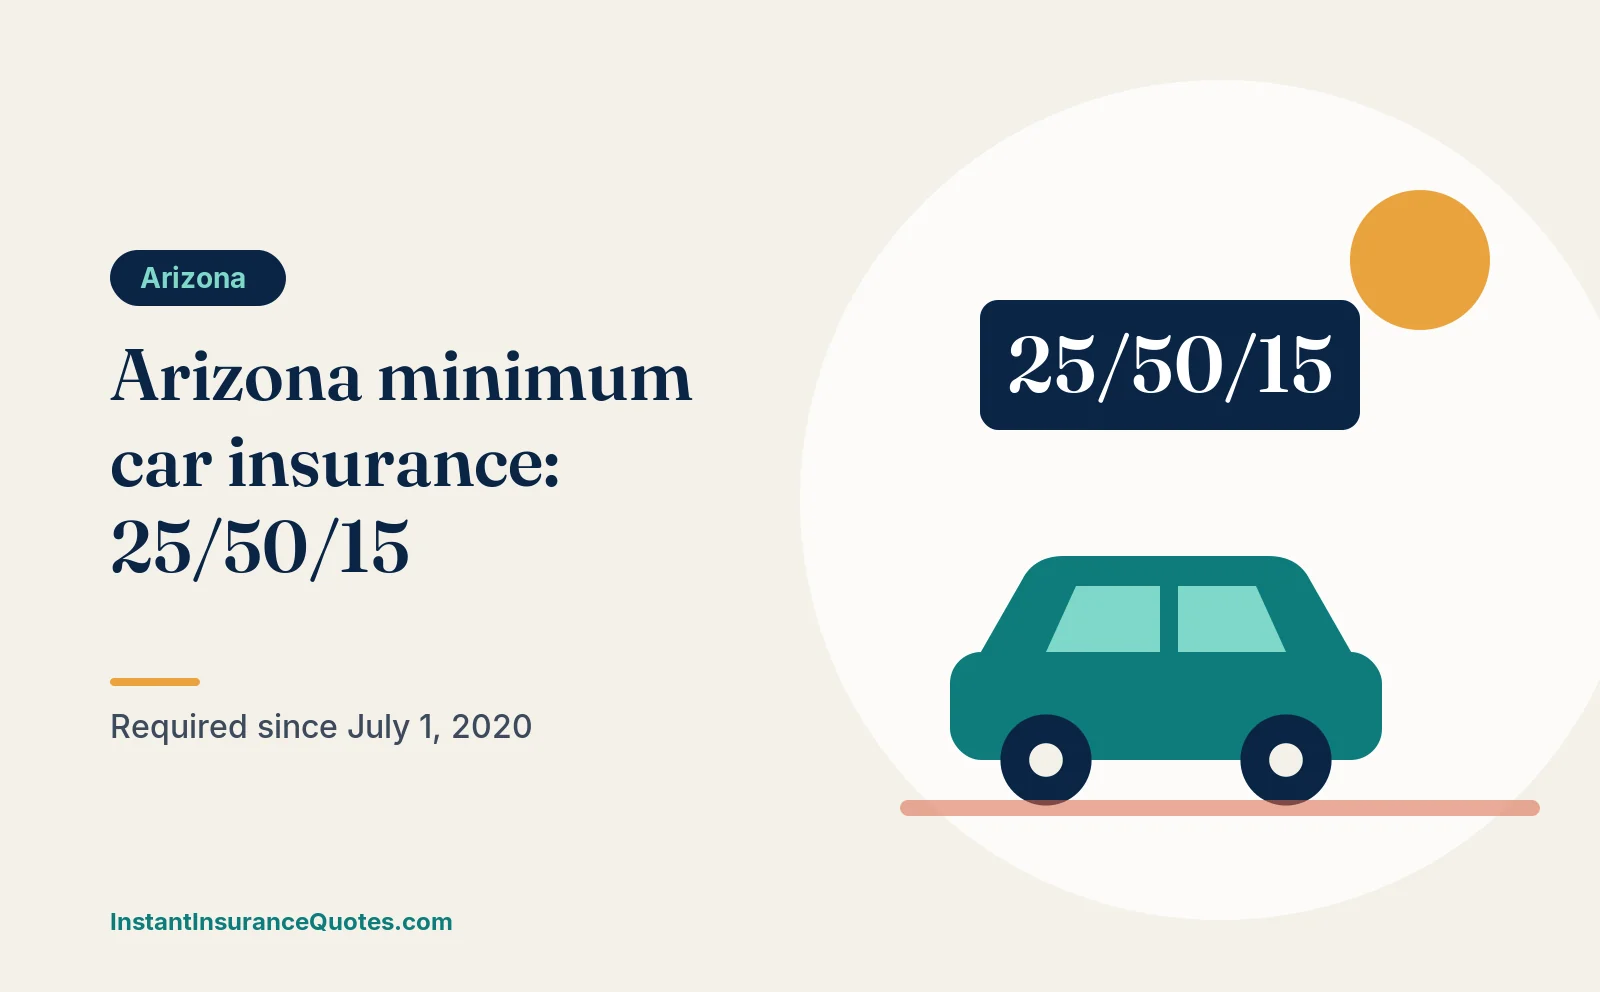
Arizona requires every vehicle driven on its roads to carry liability insurance of at least 25/50/15: $25,000 for injury to one person, $50,000 for injuries to two or more people in one accident, and $15,000 for damage to other people's property. Those numbers come from Arizona Revised Statutes § 28-4009 and are repeated by both the Arizona Department of Insurance and Financial Institutions (DIFI) and ADOT's Motor Vehicle Division.
This guide explains what the minimum actually pays for, what it leaves out, what happens if you drive without it, and how to decide whether the legal floor is enough for your household.
Arizona's required limits
| Coverage | Arizona minimum | What it pays for |
|---|---|---|
| Bodily injury liability, per person | $25,000 | Injuries you cause to one other person |
| Bodily injury liability, per accident | $50,000 | All injuries you cause in one crash (each person still capped at $25,000) |
| Property damage liability | $15,000 | Other people's cars, fences, buildings and other property you damage |
| Uninsured / underinsured motorist | Optional; if you buy it, at least 25/50 | Your and your passengers' injuries caused by a driver with no or too little insurance |
Under A.R.S. § 28-4009, the old 15/30/10 minimums still apply only to policies issued or renewed on or before June 30, 2020, and to drivers holding a certificate of self-insurance. Every ordinary policy written or renewed since then must meet 25/50/15.
What the minimum does not cover
Liability coverage pays other people when you are legally responsible. DIFI's consumer page is blunt about the limits of that protection:
- Bodily injury liability "does not pay for bodily injuries you may sustain." Your own injuries need medical payments coverage, uninsured/underinsured motorist coverage or health insurance.
- Property damage liability does not fix your own car. Repairs to your vehicle after a crash need collision coverage; hail, theft or a falling tree need comprehensive.
- If an at-fault driver has no insurance, property damage liability on your policy does nothing for your car. DIFI points drivers to collision coverage for that situation.
- If you drive to a state with higher minimums, your Arizona limits are usually read as meeting that state's minimum while you are there.
A policy that carries only 25/50/15 is often called a liability-only or minimum policy. Our guide to what "full coverage" means explains how collision and comprehensive fit on top.
Penalties for driving without coverage
Arizona law (A.R.S. § 28-4135) says a vehicle driven on a highway in Arizona must be covered, and the driver must have evidence of that coverage in the vehicle. The evidence can be shown on a phone, and showing it on a phone does not give an officer consent to look at anything else on the device.
| Violation within 36 months | Minimum civil penalty | License / registration consequence |
|---|---|---|
| First | $500 | Driving privileges suspended or restricted for three months |
| Second | $750 | Driver license, registration and plates suspended for six months |
| Third or more | $1,000 | Driver license, registration and plates suspended for one year; proof of future financial responsibility (an SR-22) required to reinstate |
ADOT adds that officers may take your license plate if you cannot provide proof of insurance at a stop or crash, and that insurers report cancellations and new policies to MVD automatically. A citation for not showing proof is dismissed if you later prove the car was insured at the time. See our Arizona SR-22 guide for what reinstatement involves.
Is the minimum enough for you?
The minimum is a legal floor, not a measure of what a serious crash costs. When damages exceed your limits, the injured person can pursue you personally for the difference. A few practical questions help decide whether to buy more:
- What would a lawsuit reach? Home equity, savings outside retirement accounts and future wages are what higher limits protect. Our free liability limit checker compares your limits with those figures.
- Who rides with you? Arizona allows a household exclusion that can cap coverage for injured family members at 25/50/15 even when you bought higher limits. Read the household exclusion guide before choosing.
- What do newer cars cost? $15,000 of property damage coverage can be used up by one late-model vehicle, before counting a second car or a storefront.
- Would an umbrella policy need higher auto limits? Umbrella insurers usually require you to carry specified underlying auto limits first. Ask before you lower anything.
Uninsured and underinsured motorist coverage
Arizona does not require uninsured or underinsured motorist (UM/UIM) coverage, but A.R.S. § 20-259.01 requires every insurer to offer it to you in writing, on a form approved by the Director, at limits up to your liability limits. If you buy it, the minimum is 25/50. DIFI notes that not every driver carries the coverage the law requires and that out-of-state drivers may carry none. Our Arizona UM/UIM guide covers the offer form and how to read your declarations page.
Before you shop
Arizona insurers may use credit history in eligibility and pricing, and most check your claims history through the C.L.U.E. database run by LexisNexis. DIFI reminds consumers they can correct errors through the LexisNexis consumer portal. Before you shop, pull your declarations page so every quote matches your current limits, then compare at least one higher-limit option. DIFI also publishes a yearly premium comparison and complaint ratio report built on hypothetical drivers in ten Arizona ZIP codes, which is a useful sense check on the spread between insurers.
Questions readers ask
What is the minimum car insurance in Arizona?
25/50/15: $25,000 bodily injury per person, $50,000 bodily injury per accident and $15,000 property damage, for policies issued or renewed on or after July 1, 2020 (A.R.S. § 28-4009).
Is uninsured motorist coverage required in Arizona?
No. Insurers must offer it in writing, and if you buy it the minimum is 25/50. You can decline it on the insurer's offer form.
Can I show proof of insurance on my phone in Arizona?
Yes. A.R.S. § 28-4135 allows the evidence to be displayed on a wireless device, and doing so is not consent to search the device.
What is the fine for no insurance in Arizona?
At least $500 for a first violation within 36 months, $750 for a second and $1,000 for a third, plus license and registration suspensions that grow with each violation.
Does Arizona minimum insurance cover my own car?
No. Liability pays others. Damage to your own car needs collision or comprehensive coverage.
Sources and further reading
Sources checked October 26, 2026. Figures are the latest published by each source at that date.
- A.R.S. § 28-4009: Motor vehicle liability policy requirements
- A.R.S. § 28-4135: Financial responsibility requirement and civil penalties
- A.R.S. § 20-259.01: Uninsured and underinsured motorist coverage offer
- Arizona DIFI: Vehicle insurance consumer information
- ADOT MVD: Insurance information and requirements
General educational information, not advice for your situation. Policy wording, state law and the insurer's decision control actual coverage. Written and edited by K.R. Not reviewed by a licensed insurance agent; confirm details with a licensed professional or your insurer. Examples use hypothetical figures unless a source is named. Report a correction.
Compare your liability limits with Arizona's 25/50/15 minimum and the assets you want to protect. Calculations run in your browser; nothing is sent to us.
Open the liability limit checkerAuto insurance: sponsored quote partners
Independent companies. We may be paid when you visit or apply. Not a ranking or a full list of the market.
Compare auto, home, renters and pet insurance options from one request.
Get quotes at Truvo →Sponsored · Affiliate linkRates, eligibility and coverage are set by each provider. Read its terms and privacy policy before applying. How we earn money.